Kim Mills: Speaking of Psychology is taking a Thanksgiving break this week, so we’re rerunning an episode from our archive. Back in 2021, at the beginning of the holiday shopping season, I talked to University of Michigan professor Scott Rick about how emotions guide our shopping behavior—and why Black Friday sales are so irresistible. We hope you enjoy this episode from the archive, and we’ll be back with new episodes next week.
Does shopping bring you joy, or do you feel a bit of pain or regret every time you have to make a purchase? Many of us will be shopping for gifts in the coming weeks—whether we enjoy it or not—so today we're going to talk about the psychology of shopping.
How do our emotions drive our buying behaviors? Why do some people spend money so easily, even when they shouldn't, while others find it difficult to splurge, even when they can afford it? Does buying a gift feel the same as buying something for yourself? Is retail therapy a real thing—can shopping boost your mood? Why are Black Friday sales so irresistible?
Welcome to Speaking of Psychology, the flagship podcast of the American Psychological Association that examines the links between psychological science and everyday life. I'm Kim Mills. Our guest today is Dr. Scott Rick, an associate professor of marketing at the University of Michigan's Ross School of Business. His research focuses on understanding the emotional causes and consequences of consumer financial decision-making, with a particular interest in the behavior of tightwads and spendthrifts, people who chronically spend more or less money than they want to, or perhaps should. The goal of his work is to understand why consumers behave the way they do and to develop interventions to improve their decision-making and well-being. He has published in journals dedicated to marketing, psychology, management, neuroscience, and economics, and his research has been covered by many media outlets, including The New York Times, The Wall Street Journal, The Washington Post, and NPR.
Thank you for joining us, Dr. Rick.
Scott Rick, PhD: Thank you so much for having me. Really happy to be here.
Mills: One of the things you're known for is developing the tightwad/spendthrift scale, so let's start there. We all know that some people spend money more easily than others, but you found there are real brain and behavioral differences between tightwads and spendthrifts and that they're related to an emotional experience called “the pain of paying.” Can you tell us more about that research?
Rick: Yeah, so that started just based on conversations. I'm personally a spendthrift raised by spendthrifts. My advisor back in grad school, George Loewenstein, was a tightwad, and I was finding a lot of people in my life seemed to be tightwads. They seemed to have a lot of distress when thinking about spending money, and that was kind of a strange thing to me, that if anything, my distress came afterwards, once I saw the credit card bill or things like that. So yeah, we did some stuff like have people shop while having their brain scanned with functional MRI, and we found some evidence consistent with this idea of a pain of paying, that people use feelings of distress as kind of the brakes on the car, so the more anxious or uncomfortable I am when thinking about spending the money, the less likely I am to do it.
Now, some people have too much of that, that's the tightwads, and that could come from lots of places, including maybe there was some financial distress earlier in life that they just can't shake later when their objective financial situation improves. And then there are those of us, like spendthrifts, who just don't have enough of it. We don't think about spending as mathematically. We're more focused on the present than the future.
And so there are these kind of big differences, and we developed a tightwad/spendthrift scale to measure this and figure out what it's different from. For example, being a tightwad is very different than being a frugal person. A frugal person, they love to save, and it's fun and they enjoy it and they're happy. A tightwad just really dislikes spending and they're not so happy and they're not buying the gifts that they should for their partner and they're not going on the vacations they should and they're walking around in shoes that hurt, even though they have the money to buy better shoes. Spendthrifts aren't on cloud nine, either. They're often in debt and kicking themselves for spending too much. We do find there's this middle ground of unconflicted consumers who have a reasonable amount of pain when thinking about spending and they tend to be happiest.
Mills: Are most of us somewhere in that middle ground then, where we're neither a tightwad nor a spendthrift?
Rick: Yeah, it depends on where you look, but around 50%-60% of the people we sample are in that big middle ground of the unconflicted consumer, and then it's about equally shared on the extremes.
Mills: It sounds like tightwads aren't really getting any pleasure out of accumulating their money, right? I mean, they just have so much pain spending it, so that's the difference?
Rick: Yeah, it's kind of anxiety maintenance, just a way to calm the fears of going into bankruptcy. When you listen to a lot of them talk about their feelings and their thoughts, a lot of them do have memories of real distress in the past, and it's just hard to shake it once things get better. It's this reaction, these feelings are cultivated over time, and it's hard to like switch it off like a light switch, so I think for them it helps to manage the distress, holding onto money.
Mills: Are spending habits related to other aspects of people's personalities, such as overall conscientiousness or extroversion, or is the tightwad/spendthrift trait just its own thing?
Rick: Yeah, no, it's related to things. Tightwads are more guilt-prone. They're a little more conscientious. It's not just conscientiousness, since they're not necessarily flossing more, or showing up to meetings on time more often, but there's some relation there. Yeah, and they tend to be a little more mathematical in their thinking. They can't shake the idea of opportunity costs: “What am I giving up later?” They really do interpret a price tag in terms of what I'm forgoing and I think they almost blow that up a little bit, like, “I'm forgoing so much by spending now,” so yeah, you can see like differences in their college majors. There are some gender differences, too. Women are a little more likely to be spendthrifts than men are, but it's not just that—it's a small relationship, but it's there.
Mills: You mentioned college majors. How does that play?
Rick: On the tightwad side, you tend to see more engineering/mathematics, whereas on the spendthrift side, you tend to see more social work or social science. But you might be thinking like, “Oh, well, how does gender relate to this?” We even find that within gender, you see these major differences. Women who are tightwads are more likely to have majored in engineering and math and women who are spendthrifts are more likely to major in social work and things like that. That's true for men as well, and so, yeah, there is definitely a different thinking style. There's a lot of people who study emotion who say that there's no emotion without cognition. It's all kind of connected. I think the thoughts and the feelings, especially for tightwads, they build on each other. The stress brings to mind thoughts of what I'm giving up later, which makes you more distressed, and it's a cycle.
Mills: One thing people may be curious about is where these traits come from and how early they develop. I know you've found evidence of them even in very young children. Can you explain that?
Rick: We have developed a spendthrift/tightwad scale for kids age five to 10. It's a very simplified thing, “Which cartoon character do you has feelings towards money that match what you have?” Even there, we get a similar-looking distribution of scores as we see among adults, kind of a similar amount in the middle, and then your two extremes. Yeah, so we're looking into how that might transfer from parents to kids through conversations, so we bring these parent/child dyads into the lab and have them talk through money situations. You do see some telltale signs, like a spendthrift parent might be—the kid might want to save and the spendthrift parent is like, “Well, are you sure? There's some cool stuff here.” I can definitely relate to that.
But again, a lot of it does seem to date back, at least among adults, to these really formative times in their life when things were really good or really bad and they just can't get past it once things change later. It's been called sometimes “post-brokeness stress disorder,” this idea that once broke always broke in terms of your feelings, no matter what your actual bank account looks like now. It's there from an early age. I think part of it is the internal wiring, what your guilt-proneness, things like that, what you're born with, what your parents instill, and then just your financial reality as a kid.
Mills: It calls to mind, though, the marshmallow test with Walter Mischel. Kids who can delay gratification. Is that part of what's going on here as well?
Rick: I think it is part of that, for sure. Tightwads are certainly better at that kind of thing, but we do find it's not kind of a general patience, that tightwads aren't necessarily patient in a lot of other domains. It really does seem to be more specific to how they think about parting with money. But if I had to, if I was forced to kind of bet on who's better able to wait for the second marshmallow, it would be the tightwad child, certainly, yes.
Mills: You've looked at how money and spending habits figure in romantic relationships and you've found that people actually tend to partner up with their opposite, that tightwads often marry spendthrifts, and vice versa. Why does that happen and how does it work out for these couples?
Rick: There's a real clear pattern that you see in sociology research of these patterns of fatal attraction, that if there's something you don't like about yourself, and then you see it in someone else, that that tends to be a real turnoff, it repels you. It's this thing that I'm self-conscious about and then I see someone else and it's just, ugh. It's enough when it's just me. I can't have a second version of that in the house. At first, it's really fun and exciting to find someone who doesn't have that issue that you dislike and we do find that tightwads and spendthrifts don't like being tightwads and spendthrifts. They're conflicted, that's why we call the people in the middle “unconflicted,” and so they tend to pair up more often than you would expect, more often than a tightwad/tightwad couple or a spendthrift/spendthrift couple.
That's fun at first, that's great. But as often happens with these fatal attractions, things get serious. You have to spend a lot of time with this person and make a lot of big decisions about where to move and how many kids to try for and that kind of thing. We are very consistent with past research in finding that the more different they are over time, the more and more they fight over money and wish they married someone else or just stayed single. I don't think that has to be the case with all mismatched couples. There are ways to, I think, manage those discussions and manage how money flows in the household. But on average, the mismatched partners seem to have a pretty rocky go of it.
Mills: How does some of those interventions work if you're in one of these mismatched relationships? Can you fix it?
Rick: I think it's good to have discussions and realize, maybe even both take the tightwad/spendthrift scale, and figure out where we are and realize that if it's a spendthrift talking to a tightwad partner, “Just realize it's not that I don't care about our future together, it's that I'm blowing household money, and I do care about our future. It's just I have this quirk. Let's try to find a way to work through it, perhaps with our account structure, like joint versus separate accounts. How obvious do we want our spending to be to each other? Do we both have to know everything right away? Or can we have some private fun accounts?”
Working with a financial counselor and/or a financial therapist I think can be a good thing. Certainly, financial therapy is becoming a more popular practice, but yeah, it can really be misinterpreted. If I'm a spendthrift and my partner is a tightwad and they get me a really terrible gift, “What, you don't love me?” No, it's not that, you just are really reluctant to spend money, but maybe my love language is gifts, but you can't spend the money, and so it can be real confusing. But if I just know that, well, it's not a love issue, it's just how you use money, then there's more understanding there. So yeah, just opening up the discussion, understanding these tendencies, and finding money flows and discussion tendencies that work for you as a couple.
Mills: But it sounds like sharing financial information is kind of important here. Even if it's not everything, right, I mean, you should share enough.
Rick: Enough, yes. I'm all about openness, but I don't know about a hundred percent immediate and active disclosure of all purchases. I think you can keep some things to yourself. Yeah, so a lot of people, for example, have this idea that the latte factor, like, “Oh, if you don't buy the latte at work, then you can save up enough money to buy a home and be fabulously rich and all that.” Some people really believe that, and so if they do, maybe I don't want to tell them about the lattes that I'm buying because it's just going to cause a fight and the lattes really don't matter that much in the grand scheme of things, so yeah, it's openness, good, but maybe there's room for discretion.
Mills: You can hide the lattes, but it's a little harder to hide that red Corvette.
Rick: Indeed.
Mills: Let's talk about gift-giving for a minute since that's a topic that's on listeners' minds right now. One perhaps surprising finding of yours is that spendthrifts seem to be at a disadvantage when it comes to giving gifts to their loved ones. Why is that?
Rick: Yeah, I think it's somewhat counterintuitive because you would think that they would be best positioned to give the best gifts, they're just willing to spend, but the issue is how do they signal that this is something different or special that I'm doing for you? If I live with a spendthrift and I see them splurging all day, every day, and then they splurge on me for a gift, it's not anything special that they've done. This is just your normal thing, so it becomes hard to signal through normal consumerist/capitalist means that I really do love you. And so I think for the spendthrift, you've got to do something different. You've got to—maybe it's an experience that you carefully plan, maybe it's something you make, but if it's just something else you pick up in your daily splurging, that's no good. It has to be a change of pace.
Mills: Well, let's talk about holiday shopping more generally. Is there any research on why Black Friday and other doorbuster-type sales are so irresistible to people? Do people feel less financial pain or emotional pain if they feel that they're getting a deal?
Rick: Sure. The framing of price, this is a low price relative to something, what it normally is or what it should be. I mean, that does help reduce the pain of spending. Scarcity is a big driver of behavior and desire. We want scarce things. You see that with young children, too, just making something appear scarce and they just crave it, so we want to get those scarce deals. I do think part of it is just misinformation and not understanding the universe of deals that are out there day-to-day. There are some unique deals that you can get on something like Black Friday, but there are some good deals out there on other Fridays and just in general, so we don't need a stampede there. It's just historically we know that this has been the case. I think the landscape's very different now, so I think it's just a lack of shopping expertise or information.
I would also add that it's just something to do. A lot of people are off work. A lot of people are with their family, and if you've just kind of gone through Thanksgiving with them, you might need some air, so to speak, so it's a way to step away from too much family time, I would say. A little goes a long way sometimes.
Mills: Well, that raises the question then about online shopping. You seem to be intimating that there are bargains out there every day, so do people behave differently when they shop online versus when they shop in person, or are the same psychological factors in play?
Rick: Well, certainly, yeah, many of the same ones are in play, but online shopping, it's just adding fuel to the fire. It can be so effortless to pay, especially if you have all your information saved already, just a couple clicks and you're out of there. You don't even know what happened. It's just like you get carried away. If you want to control that, you got to put up speed bumps. You got to erase your information. Don't have it, save it, log out. Do the Amazon save for later or put it in my list instead of buy now. Try to enforce some kind of waiting period, whereas in the store, you have to get in the car, you have to wait in line. There are all these opportunities to second guess it, but with a lot of online or mobile shopping, it's just so seamless. But the in-person retailers are catching up. There are these Amazon Go stores where you just swipe your phone when you walk in and then you just pick up whatever you want and you just walk out. There's no checkout.
Mills: Yeah, that's a scary idea.
Rick: Yeah. Retailers are really skilled at distracting you from the moment of payment. Well, here in Ann Arbor have Von Maur. It's like the Nordstrom of the Midwest and their sales associates are very nice, very chatty, and before I go to the register, I have to think, “Well, what am I doing this weekend?” Because I know they're going to ask. I can't just say something lame like, “Well, whatever my wife thought of.” I have to have a story. By the time I'm done, I have these bags, I don't even remember paying for it. It's just like, “What happened?” They're good at taking your attention away from pulling out the wallet and how much you actually spend.
Mills: Then there are little tricks, like you walk into Target and they've got these little displays of sort of junkie stuff. They prime you, right, so, “Oh, I'll just pick one or two of these things,” and then pretty soon, you're in the back of the store and your cart is full.
Rick: Well, the Target people, they're artists. I mean, yeah, that's all about shopping momentum. You want to get something in the cart—you want to get that wallet opened right away. Then people just get into just a different mode, a different mindset, so yeah, you got to break the seal as soon as they walk in.
Mills: Then they've got those big baskets, right, which, “Oh, I'll get this comforter because there's plenty of room in here.”
Rick: The baskets are very accommodating, yes. I've never had one with a squeaky wheel, either. It's just smooth sailing.
Mills: Let's talk about gifts again for a minute. Is buying a gift the same as buying something for yourself in terms of the emotions that you experience? Are you more or less likely to experience the pain of paying when you're buying somebody a gift?
Rick: All the evidence we have does suggest that it's less painful to buy the gift, but there are other emotions that could be in play, like anxiety, “Will they like it? What will they think?” It could be a much more stressful experience. It's just more charged. There's anxiety, but there's joy. We do find that tightwads look less like tightwads when they're buying gifts. What we were saying earlier about the spendthrifts buying gifts, I think the tightwads are in a real nice position. If they're normally buying cheap things and then you buy something really fancy for me, I'm like, “Oh, my gosh. I know this was hard for you. Given how you normally spend, this was a big change for you. That's amazing.” I'm actually not sure that's true, because if the tightwads don't experience pain when they're buying the gift, then they getting too much credit there, so I think they're in a nice position as gift-givers because they've set the expectations. But yeah, it's just a very different process, much more emotionally charged.
Mills: What about everyday purchases, such as groceries or gas or necessities? For tightwads and spendthrifts, is the emotional experience of making everyday purchases the same as when they buy something frivolous or unusual?
Rick: Yeah, so for things that are routine or necessary, the pain does seem to be muted or less influential because these things are just expected purchases. You really do see the biggest differences between the two types on things that are optional, things that make you think, like, “Do I need this? How long will I like it?” so I wouldn't expect big differences in what they're spending on gas or milk or you commodity kind of stuff, but really, it's things that seem optional. But of course, marketers are very skilled at framing optional as necessities or investments: “This is not a pleasurable massage, this is an investment to help your back feel better, and you'll be a better parent and a better athlete or employee,” or whatever. That kind of framing that can really work on tightwads if it's, “Oh, well, okay. I didn't think of it like that.” But spendthrifts, they don't need that. They're very skilled at viewing everything as an investment, even if it's just an investment in like, “Oh, I'll have a cool story to tell.” That's one thing we are good at, we're good at thinking of reasons for purchasing.
Mills: The idea of retail therapy gets a bad rap, people using shopping to act as a pick-me-up or to make themselves feel better after a breakup or a bad day, but you've done some research that found that, at least for some people, there are some truth to the idea of retail therapy, that there's a benefit. Can you talk about that?
Rick: I've heard all the bad things about retail therapy and how it's foolish and a big waste and it doesn't work. As a spender—of two studies, emotions and financial decision-making, that just did not sound right to me. It seemed inconsistent with what we know about emotional experience, and in particular, the experience of sadness. There's a lot of work suggesting that sadness is associated with thoughts of, “I'm not in control of my own destiny. I am at the mercy of external forces, the environment, random chance.”
There's also other work suggesting that making choices, especially pleasurable choices, can increase your sense of control, the sense that you are the captain of your own destiny, “I want this, not that. I'm in charge.” And so we thought that when people are sad, that the experience of saying, “Yes, this. No, that. I'm making choices,” that could stop those thoughts of, “I'm not in control. I'm at the mercy of the environment.”
We thought we could interrupt that pattern of bad thoughts and bad feelings by having people make those choices, and so that's what we did. We did experiments where we made people sad and we had them watch terribly sad film clips and then we would have them do kind of shopping choices or we would still expose them to products, but they wouldn't get to make a choice, just browse. I think browsing is also underrated, but it's not choosing. The choosers—they got over their sadness faster than the non-choosers, that by exercising this control over something, they were able to get over it more quickly. It really does seem to be about the choosing. It doesn't seem to be about, “I get to acquire something.” Even when it's hypothetical choices, they still got over their sadness more quickly. I should say it doesn't work for anger. We didn't find it works for anger. Anger tends to be about other people, “I'm mad at you. You've wronged me.” I'm not sure I can shop that away, if my boss is being mean to me.
Mills: Right, right. I'm not going to buy a pair of shoes and feel better.
Rick: Yeah. I mean, yeah, you might like the shoes, but I think you're still going to have that anger. But yeah, sadness, that does seem to be affected, helped by making these choices. Of course, disclaimer, is this a long-term solution? Is this something you should do every pang of sadness? I'm not so sure. I don't think it needs to be an expensive thing. We found that, again, even for hypothetical choices, so give yourself a budget for this kind of thing. This is a small budget. This is like a nice restaurant meal should be the max, I think, that we're dealing with because if you keep doing this and you get in debt, then that itself will make you sad, and we don't want that. But I think used judiciously, shopping can be a nice remedy for sadness.
Mills: Well, so what's next on your research agenda? What questions are you trying to answer now?
Rick: Looking into more deeply this idea of what is best for marriage, joint or separate accounts and for different kind of couples, including couples that make very different income. How do you manage those income differences? There was a lot of old work suggesting that joint accounts are good for couples, but that older work could not rule out the possibility that, well, maybe it's just happier couples that chose to join accounts, like, “We really love each other. We're in it for the long haul. Let's merge everything.”
What we did and what we're kind of writing up now, we did this field experiment with engaged and newlywed couples who had separate accounts and we randomly assigned them to keep it separate or make a joint account and just use that or do whatever you want and we followed them for 2 years. What we found was that the couples that we forced to do the joint account, they were happiest 2 years later. They were most seeing eye-to-eye on financial matters 2 years later. This is at least among couples who were open to our experiment. They were at least, I think, toying with the idea of, “Maybe, should we go joint?” and we just kind of forced them to do it, “Just do it,” and it helped. I don't think every couple should go joint. There are some bad couples out there where things are kind of shaky, right?
Mills: Sure.
Rick: Maybe best to keep one foot out the door, so to speak. But yeah, so we're looking into some other situations in which joint accounts might help. We're looking more into things like the post-brokeness stress disorder that's been discussed, how those formative experiences of financial strife early in life can stick with you and what could be done to get people to understand, “Oh, I do have money now. I do have money to spend. Things are okay. I can shake those feelings of anxiety.” Yeah, and of course, a lot of work on parents and kids still to be done.
Mills: Well, Dr. Rick, this has been really, really fascinating. I hope people have gotten some good information regarding how they're managing their finances. And again, this has been really interesting. I appreciate you taking the time today.
Rick: Thank you so much.
Mills: If you’d like to find out where you fall on the tightwad/spendthrift scale, you can find a link in the show notes on our website, at www.speakingofpsychology.org. You can also find previous episodes there, or on Apple, Stitcher or wherever you get your podcasts. And please leave us a review. If you have comments or ideas for future podcasts, you can email us at speakingofpsychology@apa.org. That’s speakingofpsychology–all one word–@apa.org. Speaking of Psychology is produced by Lea Winerman. Our sound editor is Chris Condayan.
Thank you for listening. For the American Psychological Association, I’m Kim Mills.

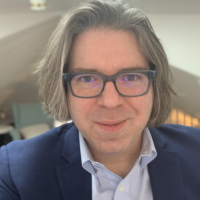 Scott Rick is an associate professor of marketing at the University of Michigan’s Ross School of Business. His research focuses on understanding the emotional causes and consequences of consumer financial decision-making, with a particular interest in the behavior of tightwads and spendthrifts. The overarching goal of his work is to understand when and why consumers behave differently than they should behave (defined by an economically rational benchmark, a happiness-maximizing benchmark, or by how people think they should behave), and to develop marketing and policy interventions to improve consumers’ decision making and well-being.