Kim Mills: Anyone can be targeted by a financial scammer, but many older adults are especially at risk. Scams targeting people over age 60 cost victims more than $3.4 billion in 2023. According to the FBI’s Internet Crime Complaints Center, the average victim lost nearly $34,000. Not all older adults are at high risk, but researchers are finding that financial vulnerability could be an early sign of cognitive impairment or even Alzheimer’s disease.
So how prevalent is financial fraud and abuse? What vulnerability factors put some older adults at particular risk? What’s the connection between financial vulnerability and changes in the brain? And what can people do to protect themselves and their loved ones from falling victim to a scammer? Welcome to Speaking of Psychology, the flagship podcast of the American Psychological Association that examines the links between psychological science and everyday life. I’m Kim Mills.
Today we’re coming to you from Denver, Colorado, where APA is meeting for its 2025 annual convention. My guest today is Dr. Duke Han, who will be speaking at the convention later this week. Dr. Han is a professor of psychology, family medicine, neurology and gerontology at the University of Southern California. He’s a board certified clinical neuropsychologist, an APA fellow and a fellow of the National Academy of Neuropsychology. His research focuses on factors that affect cognition and decision-making in aging, with a particular interest in financial decision-making. His work has been featured in many media outlets including CNN, Reuters, and PBS.
Dr. Han, thank you for joining me today.
Duke Han, PhD: Oh, thanks for having me, Kim. This is great. I’m a big fan of the show and so it’s good to be here.
Mills: Oh, thank you.
So let me start by asking you: How common are financial scams and predators, especially the ones who prey on older adults? Do we know, for instance, how many or what percentage of people might be victimized in their lifetime?
Han: So to answer your question briefly, we don’t have great numbers on this. And the reason for that is because there aren’t any central tracking programs from the government or elsewhere that have been effective in tracking how bad of a problem this has been. Now we know from research that we think, or at least people report this in about five to 10% of the older adult population, but many of us who do research in this area think this is a huge underestimation of what this problem actually is in our country. And really no one really knows how prevalent this is. I will say I give talks on this topic frequently and after each talk, a number of people come up to me and say that this has happened in their life, in their family. And so I think it’s a lot more prevalent than what we think.
Mills: What are the most common types of scams? And are most of these scams online now or are they still happening by phone or even snail mail?
Han: So it’s interesting that the prevalence of scams seem to be very focused on the age range, actually, of the victim. And so in, I would say in early older age, there is a lot of prevalent email scams, phone scams. If you go a little bit older, the phone scam becomes more prevalent and less electronic scams, just because I think there’s less utilization. And then in the oldest age groups, believe it or not, just snail mail is actually one of the most prevalent ways to scam older adults. And I think it’s, again, because it’s just more utilized.
Mills: And how would that work? I mean, snail mail, it feels so ancient these days. I mean, somebody sends you a letter and says, give me all your money?
Han: Yeah, there’s lots of really sad cases of older adults being sent letters saying help support this issue or this cause, and those causes being bogus actually. And because older adults are very generous and kind, they often end up responding to those calls for financial support. And I think I can share this, that the postmaster, this is something that the postmaster has to deal with on a pretty wide scale. And so they are very interested in trying to address this, particularly older adults.
Mills: Are most of the scammers strangers, or do people get scammed just as often by friends and relatives?
Han: Yeah, that’s another great question. So we have done some research using some available databases to see how prevalent the type of scammer or what type of scammer might be committing these crimes. And it does seem to be the case, at least in certain crimes, that family members unfortunately are very commonly the ones that are perpetrating this. Now that being said, we also know that scam and fraud is very prevalent from electronic- or stranger-based locations. And a lot of these are actually outside the United States and people from outside the United States just trying to scam older adults in the United States. So there really is a range, and again, we don’t really have great data to know how prevalent, what type of scammer is versus another.
Mills: I have an acquaintance who I think right now is being scammed by somebody. And this person started out as a stranger and now he thinks he’s having some kind of an online relationship with a woman who is probably some strange man in a foreign country. I mean, is that a very common technique that works well, particularly with older people?
Han: Sure, yeah. So this is a common scam known as a romance scam or it could be a romance scam. It doesn’t have to be even romantically involved, just some sort of interpersonal relationship scam. And unfortunately, loneliness and social isolation is one of the biggest risk factors for a scam or fraud or financial exploitation, vulnerability. And this is a scenario where a stranger will try to become more familiar with an older adult because that older adult has more resources and that older adult might be feeling more lonely and may be very responsive to those overtures. And that’s a situation where you don’t necessarily need to have any cognitive impairment involved. It could be sheerly just an older adult feeling more lonely and more isolated. And in those cases, it’s sad because often these strangers become a very close to these older adults and these older adults trust these strangers, these bad actors with a lot more of their resources than they should. And so these are situations that are fairly common that we hear about.
Mills: So you’re a clinical neuropsychologist, what got you interested in financial vulnerability?
Han: So I had always been interested in the earliest signs of Alzheimer’s disease. And from a cognition standpoint, I had always been interested in what are the first signs of cognitive decline that might indicate Alzheimer’s disease down the road. And that’s been a basis of my research for many years. And at the same time, I was seeing patients for dementia evaluations. And I remember vividly at one point in my career where I had a patient referred, one after the other, because it was presumed they had dementia because it was discovered they were giving away large sums of money to a stranger just like we had been talking about. And that was a change in behavior that had never happened before. And there was this general presumption from the family and the medical providers, oh, this is actually early dementia, let’s get it diagnosed. And so they would send me these patients and I would do hours of testing on these patients and they would test cognitively normal.
And so clearly there had been a change in behavior. Our cognitive tests weren’t picking up on the fact that there was any cognitive impairment. And so that was a bit of a disconnect. And often the family and the medical providers were disappointed because it just made things less clear. The patient often loved it because it gave them license to keep doing what they were doing. But for me as a clinical neuropsychologist, it made me realize there’s really a lot that we just don’t understand about the relationship of financial decision-making in older age and cognition and early Alzheimer’s disease or early dementia. And so that got me thinking, could this be one of the earliest signs of dementia even before any cognitive impairment is noticed? And I was working with an Alzheimer’s research center at the time, the Rush Alzheimer’s Disease Center, which is an amazing center based out of Chicago. They had started doing research studies on this topic and then one thing led to another and it sort of took off as a research focus from that point on.
Mills: So since then, some of your research has found that there is a connection between financial vulnerability and early signs of Alzheimer's disease in the brain. Can you tell us about that work?
Han: So we had a study recently published that focused on older adults that had no signs of cognitive impairment, but also varied with respect to their financial vulnerability status. And in this study we found that a brain region called the entorhinal cortex was thinner in older adults who were more vulnerable to financial scam and fraud. And again, this was in a group of people with no cognitive impairment. And so another aspect to this particular study in this particular brain region that’s important to understand is that this brain region, the in entorhinal cortex, is commonly known as one of the first brain regions to be impacted by Alzheimer’s disease neuropathology. So what we saw in this study was that older adults who had thinner entorhinal cortex, presumably because they were starting to accumulate Alzheimer’s disease neuropathology, showed greater vulnerability to financial scam and fraud. And again, these are older adults who had no cognitive impairment.
So this helps us understand why certain older adults might show poor financial decision-making ahead of any noticeable cognitive impairment. It could be that they’re showing brain changes consistent with early Alzheimer’s disease before any noticeable memory decline.
Now, I’ll also say that the entorhinal cortex is an interesting and important brain region for financial decision-making because it connects a brain network that helps us imagine future outcomes. So it also connects another brain network that helps us assess the value of certain things, the value of certain outcomes. And so you can imagine if a brain or if an older adult has thinning brain in this particular region that helps connect the ability to imagine certain outcomes and the ability to assess appropriate value, that that particular older adult might be more vulnerable to scam and fraud and financial exploitation. So all of these things come together to really help explain why certain older adults might show poor financial decisions ahead of any noticeable cognitive impairment. It could be that they’re showing less thickness of the entorhinal cortex, because this is commonly known to be one of the first brain regions impacted by Alzheimer’s disease.
Mills: Do any of the people you’ve studied have sort of a cognizance of their own that something is going wrong? I mean, they may have begin to understand that they’re giving away their money, and are they beginning to see also that perhaps they’re losing some of their executive function?
Han: This is something that we often get asked by people outside of our research program, how come these older adults don’t know that they’re making these poor financial decisions? In our research, it’s been interesting. We’ve been trying to delve into that a bit more. Many older adults don’t really think they’re making poor financial decisions. And so there is that lack of insight potentially in what they’re doing.
In a really interesting twist, I think some older adults fully are able to articulate that they’re making poor financial decisions and they still do it. Even if you explain to these older adults, well, you just told me that this is probably not a good decision. Why do you keep doing it? They’ll say things like, Well, it’s because I just want to. And so some might argue maybe that is still a lack of insight actually, but honestly, we still haven’t really fully understood the link between insight and financial decisions, but it’s something that we’re hoping to learn more about.
Mills: So it’s not always a sign of Alzheimer’s or any other kind of mental decline when these things are happening, but is something else going on in people’s brains, or they just are gullible and they’re just looking for a friend? They trust somebody and then they decide to give away their life savings.
Han: So we’ve been doing this work for quite some time now, and we do believe that a portion of older adults do show brain changes that are consistent with early dementia ahead of any noticeable cognitive decline. Now that being said, we also believe that some older adults may not show any brain changes consistent with dementia and might be showing poor financial decision making for other reasons such as they may be lonely or they may be socially isolated. Doing this work for a number of years now, I’ve grown to appreciate there really is a host of different reasons why certain older adults might make poor financial decisions in certain situations. Now, I do need to also stress that it’s really just a portion of older adults that might be more vulnerable to scam or fraud or financial exploitation.
Also, in this work, I’ve come across the notion that some believe that as we grow older, we’re all going to be poor financial decision makers. We’re all going to be more susceptible to scam or fraud. And I emphatically have to say that that’s not the case. There’s lots of data to support, actually, the vast majority of older adults won’t even show cognitive impairment as they grow older. They’ll just show normal cognition with respect to their age. And so I did want to just take a brief aside and say that way of thinking is, in my opinion, very ageist. It’s not that all older adults are going to show poor financial decision making or even show cognitive impairment, but we do believe that a portion of older adults may become more vulnerable to scam or fraud or financial exploitation because of brain changes or because of other risk factors such as loneliness and others that we’ve studied throughout the years.
Mills: What can people do to protect themselves, or what can their family members do to protect other members of their family as they’re aging?
Han: Great question, and this is a question that I always hope someone will ask during an interview, so thank you for asking it. We do believe that some older adults may show brain changes consistent with early Alzheimer’s disease or dementia or cognitive decline. And so I think monitoring of cognition and brain health, just general brain health, a focus on brain health and older age is one way to address this. For all older adults, we had been talking about social isolation. That’s another risk factor. It’s a very strong risk factor in the elder abuse research world. It predisposes certain older adults to abuse and financial exploitation. So another way that an older adult could be protected, or at least this could be at less of an issue, is reducing a social isolation of older adults, increasing frequency of contact, developing meaningful relationships. We have a study showing that it’s not just how many people an older adult knows that is protective, it’s really how deep of a relationship they have with even just a few people. That aspect is protective against financial scam and fraud.
Other things like general health promoting behaviors are helpful. So for example, we have a study showing that frailty is associated with higher financial exploitation, vulnerability in older age—and by frailty, specifically hearing and seeing. So even just staying on top of declines in vision or especially declines in hearing, the use of hearing aids and things like that, are going to help protect older adults against scam or fraud or financial exploitation.
So I think also just general awareness that these things are happening is a good thing. So education programs that bring awareness about scam and fraud of older adults. This podcast that we’re doing right now, any media interest, I think that helps bring attention to this matter. The more that the word gets out. I think this helps to bring attention to things that could be scam or fraud.
It also helps, I think, to reduce some of the stigma and the shame because this is truly something that can happen to anyone. It doesn’t mean that you’re going to develop Alzheimer’s disease or that you have poor cognition. Anyone can make a poor decision. I can tell you in our own research, we have very highly educated doctors and lawyers, participants in our research program. So it can happen to anyone. It’s really not something that is going to happen to just because you grow older. So stories like this, I think go a long way to help reducing the stigma and the shame behind this when it does happen.
And then I will say finally, if it does happen, I would encourage anyone listening to report it to, there’s lots of reporting methods now. So IC3.gov is something that was developed by the government. It’s a website, and that’s to report any sort of internet scam or fraud. The Senate has a hotline about this. AARP has a their fraud watch program, which has a number of different resources to try to address this. So if unfortunately it does happen, I would encourage anyone to please report it because in the reporting that helps to protect others from the same fate.
Mills: And I think at least—I know my financial institutions ask me to have a designated other person on a lot of my accounts so that somebody else would have the ability to look in and not really do anything but know if something strange were happening.
Han: Yes, and I think programs like that go a long way to help. And I think if older adults are willing to engage in those programs, I think again, it’s the more people that are involved that are looking out for the welfare of older adults, I think that actually goes a long way to help protect against really this epidemic of scam and fraud among older adults, which is happening right now.
Mills: Are there other policy changes that you think might help prevent these scams?
Han: So there are many in our field that believe that having harsher penalties for people who commit these crimes might be helpful. That could help. I actually, it’s not my area, so can’t really speak to that. We had mentioned some of the public education programs, I think go a long way to help address this. In terms of policy, I think we started off this conversation with the fact that there aren’t really great tracking programs. And if there was a great tracking program, one that would help older adults feel less shame and guilt about experiencing this and being able to report that so that we can track and see how bad this problem is and have real good data, I think that would go a long way to help address this problem as well.
Mills: What else are you working on right now? What are the other big questions that you want to answer as a neuropsychologist?
Han: So we are still pursuing this as a potential early marker of Alzheimer’s disease, dementia. And so one of the things that we’re doing right now is we’re developing ways to actually look and use very, very new blood tests that have been developed for Alzheimer’s disease specifically. So we’re hoping to incorporate some of these blood tests in our research. We are still very much interested in early brain changes. We’re still very much interested in all the other factors outside the brain, so social relationships, social isolation, medical health, other factors, other contextual factors. We are very interested in how this might look in different underrepresented people groups. And so that’s something that we really don’t have great data at all on. And we know that generally speaking, older minoritized people groups are targeted more or they experience more scam or fraud. And we need to know that why that’s the case and we need to try to address that. So these are just some of the questions that we’re trying to focus on in the future.
Mills: Dr. Han, I want to thank you for joining me today. It’s really been great seeing you here in Denver.
Han: Really great being here with you, Kim. And thanks again for having me on your program. Big fan.
Mills: You can find previous episodes of Speaking of Psychology on our website at speakingofpsychology.org or on Apple, Spotify, YouTube, or wherever you get your podcasts. And if you like what you’ve heard, please follow us and leave a review. If you have comments or ideas for future episodes, you can email us at speakingofpsychology@apa.org. Speaking of Psychology is produced by Lea Winerman.
Thank you for listening. For the American Psychological Association, I’m Kim Mills.

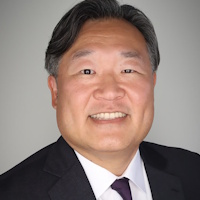 Duke Han, PhD, is a professor of psychology, family medicine, neurology, and gerontology at the University of Southern California. He is a board-certified clinical neuropsychologist, a fellow of the American Psychological Association and of the National Academy of Neuropsychology. Han is interested in factors that impact cognition and decision-making in aging.