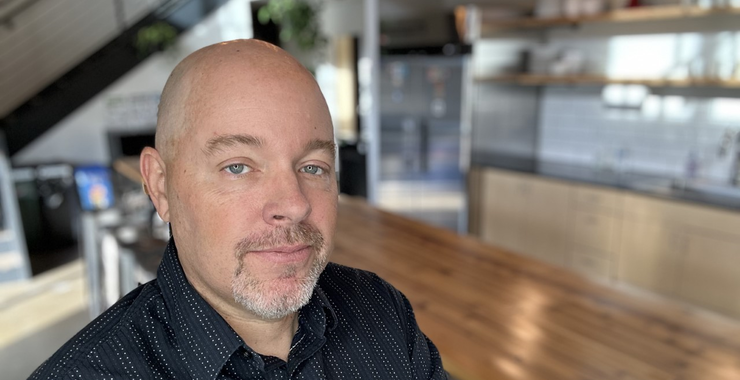
Clinical psychologist and financial planner Brad Klontz PsyD, CFP®, thinks all clinical psychologists should be much more intentional about helping patients deal with their feelings and belief systems around money, because money is one of the top stressors in the lives of Americans. Two-thirds of respondents to a poll conducted this year on behalf of APA, Stress in America 2022, identified money as a significant source of stress, and that’s consistent with responses with past years as well.
“To me, it’s a call to action,” Klontz says. “In your practice, ask people their level of financial stress, how much debt they have, how they get along with their partners around money. Who better to help people with stress around money than psychologists?”
Klontz, who now works as a financial planner and educator, believes he was among the first to work in the emerging field of financial psychology. He has done researchopens in new window and written a number of books on the topicopens in new window, and he maintains a strong social media presence—he has more than 800,000 followers on TikTok—aimed at reaching young people in particular with his findings on the psychology of wealth. Klontz has developed a questionnaire to determine which of four approaches to money, or “money scriptsopens in new window,” influence a person’s ability to build and enjoy wealth.
Only one of the four money scripts Klontz has identified leads to financial wellness and prosperity, and that’s “money vigilance,” which accepts the importance of keeping money in perspective and saving for a rainy day, he says.
Less helpful are beliefs like “money status,” which moves people to tie their self-esteem to how much money they have (and flaunt), which can lead to overspending; “money worship,” the belief that money is the key to happiness, which leads to a feeling of emptiness and to overspending; and “money avoidance,” the belief that money is bad, and that wealthy people are greedy or corrupt. Money avoidance can lead people to sabotage their own ability to accumulate wealth, he says.
“If you want a different outcome, you should perhaps take some time to examine your beliefs,” Klontz says. The problem usually is not “a lack of information or a lack of financial literacy, it’s a lack of understanding of their own psychology. Psychologists are in the best position to help people with that.”
Early experiences can skew our relationship with money
Klontz became fascinated by the psychology of money after he himself, a newly minted psychologist burdened with $100,000 of student debt, put what money he had into the stock market at the height of the dot-com bubble of the late 1990s, and promptly lost most of it. Wiser but broke, he says he sat his parents down and interviewed them, asking, “Why are we the way we are around money? I was trying to sort out my own psychology around money,” he says.
Klontz says he didn’t set out to be a test designer, but he needed tools to assess financial beliefs and behaviors, which didn’t exist when he was starting out. An APA Fellow in Division 42opens in new window, Psychologists in Independent Practice, and a former president of the Hawaii Psychological Association, Klontz has done considerable research over the course of his career. His most recent book is Psychology of Financial Planningopens in new window, written with educators Charles R. Chaffin, and Klontz’s father, Ted Klontz. One of the earliest areas he explored was why financial stressors are not addressed in therapy as a matter of course. “I saw an opportunity to expand our understanding in that area,” he says.
Cognitive psychologists had looked at biases people have around money that are “ubiquitous, universal,” Klontz says. Nobel Prize recipient Daniel Kahnemanopens in new window, PhD, worked with the late Amos Tversky to identify a number of biases, like loss aversion, that affect humans’ ability to make good decisions when risk is in play. Kahneman and Tversky’s workopens in new window led to the creation of an entirely new area of economics, deeply informed by psychology, called prospect theoryopens in new window. And there is a body of work on pathological gamblingopens in new window as well, Klontz says. But he was interested in what we learn from our families, and from early experiences, that skew our ability to have a good relationship with money.
“It’s not just errors in thinking, it’s also developmental psychology, multicultural psychology, family systems. It brings in all these other areas of psychology to help understand financial behaviors,” he says.
Financial planners value psychological insights
Financial planners have been “very receptive to this whole psychology angle,” Klontz says. They are likely to have experienced firsthand the frustration of advising clients about how best to set themselves up financially for the future, only to watch those clients fritter their money away, or get into a conflict with family members over how to proceed, or simply avoid thinking about it. Not only that, but Klontz found that many financial planners his team surveyed had developed posttraumatic stressopens in new window after the 2008 financial crisis, which could have had long-term effects on their ability to effectively advise their clients.
The psychology of financial planning is now considered an important area of study in that field, and 7% of the questions on the certification examination offered by the Certified Financial Planner Board of Standards have to do with psychology.
While consulting with financial planners on his research, Klontz became interested in the work, took classes and became a certified financial planner (CFP) himself. He presently does not see patients as a psychologist. If he did, he would never wear both hats with the same client. “You cannot be somebody’s financial planner and their therapist, period,” he says.
Klontz is an associate professor of practiceopens in new window at Creighton University’s Heider College of Business in Omaha, Nebraska, which offers an online master’s degreeopens in new window in financial planning and financial psychology, and an online graduate certificateopens in new window in financial psychology and behavioral finance. He is also a cofounder of the Financial Psychology Instituteopens in new window in Nashville, Tennessee; and a managing principal of Your Mental Wealth Advisorsopens in new window in Burlingame, California.
Klontz said he believes that, in terms of money scripts, his fellow psychologists tend toward money avoidance. “We’re drawn into the field to help people,” not to make money, he notes. “People are sharing the most intimate parts of their lives with you and then you’re getting money from them for it,” and that can be uncomfortable for some practitioners, he says.
That discomfort has been codified to an extent, he says. Klontz remembers a teacher telling the students in one of his graduate school classes, “‘We’re here to help people, not to make money,’” he says. “Coming from a lower-income home, I was like, ‘Well, actually, I was hoping to make some money, too, at least at least enough to pay off my student loans.”