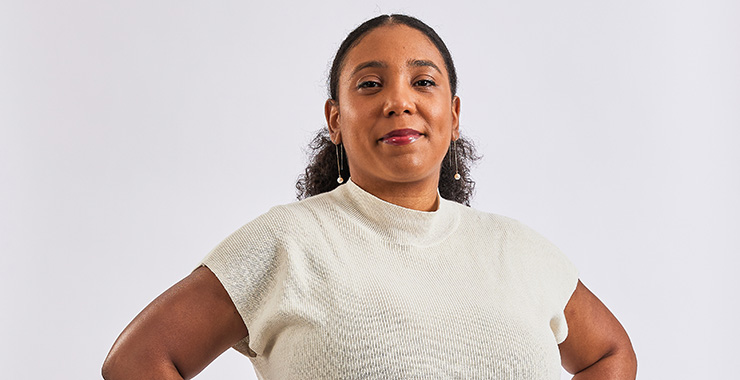
Wendy De La Rosa, PhD, an assistant professor of marketing at the Wharton School at the University of Pennsylvania, first developed an interest in understanding how money shapes people’s decisions when she was a young child of a non-English-speaking immigrant. Part of her responsibilities included acting as a translator for her mother, whether it was reading credit card statements, bank notices, or other financial documents. Given this early exposure to her family’s finances, she started to notice the many ways in which money was an invisible presence sitting at their dinner table, dictating her mother’s moods, and driving their decisions. “I became obsessed with thinking about how this resource shapes our lives,” said De La Rosa. After obtaining her PhD in marketing from Stanford University and helping to start a behavioral economics unit at Google, she accepted the position with the Wharton School. She is also the cofounder and cohost of the TED series Your Money and Your Mind, which offers behavioral science-backed strategies for achieving a more secure financial future.
The Monitor spoke with De La Rosa about her research into the connection between finances and well-being.
Why is it so important for psychologists to think about financial decision-making?
When people don’t feel financially secure, it manifests itself in so many ways, whether it is increasing their anxiety and their stress or decreasing their ability to engage in complex thinking. If your mind is preoccupied with something else, it is hard for you to dedicate resources to other things.
I think it’s imperative for everyone, psychologists in particular, to think about the impact of financial anxiety and how it can manifest itself against many different domains of life. There’s an assumption that as a person moves up the income spectrum, they tend to have fewer worries about finances. What we are recognizing is that a person’s perceptions about their wealth, which we call subjective wealth perception, is positively correlated with their objective wealth, but the correlation isn’t always one-to-one. You can have someone who is objectively earning a lot of money but feels as though they are in a world of scarcity and vice versa.
It is always important to understand what subjective wealth perceptions people have, because this is going to be more predictive of their spending behavior and their self-reported stress than their objective wealth. A person’s perception of their financial situation is often more important than their objective financial status.
In what ways are these perceptions of financial well-being critical to a person’s mental well-being?
A person’s subjective wealth perception is their financial situation compared to a relative benchmark, such as their own budget or the income of those around them. For example, a person may feel great about earning $70,000, but once they find out their coworker makes $75,000 or $80,000, they suddenly start to feel stress and anxiety. We’re social creatures by nature, so we engage in this comparative behavior.
How does financial status impact behavioral health?
We have to recognize that this is not only a problem for compulsive shoppers or chronic overspenders. Nearly three quarters of Americans feel stress about money at least some of the time. There’s this constant state of stress that most of us are feeling. That level of stress, whether it is overwhelming or not, can manifest itself in a number of different ways, but it all boils down to a sense of a lack of control.
In American society, there is this belief that financial success is a consequence of individualistic behaviors, that people are successful because they worked really hard. There isn’t a recognition that a lot of people are really successful because of inherited wealth, because of help from others, because of luck, and, yes, because of hard work.
When we feel like we are not doing well financially—because we think financial success is such an individual endeavor—we tend to feel shame. One of the best things that psychologists can do is to untangle that shame.
What are some of the behavioral changes related to finances that psychologists can help people make?
Step one is helping people understand that we are in an environment where every company is getting smarter, faster, and better at getting you to part with your money. It’s almost a David versus Goliath situation, and it’s OK that you are struggling with this situation because it’s actually really hard.
From there, it’s important to talk about some of the behaviors that we should change. It could be automating financial decisions so that someone isn’t constantly ruminating about their finances. One thing a person can do is to create set-and-forget strategies, such as automatically moving a percentage of their paycheck from their checking account to a savings account. If they don’t get paid, they don’t need to stress, because no money comes out. And if they get paid a lot, they’re going to save more. But they won’t have to worry as much in that regard.
The other step is to help people understand how they can regain a sense of control. A lot of people feel out of control with their credit card debt. One thing people can do to regain control is to call their credit card company and change their payment date so that it aligns with their pay frequency. Maybe the 25th of every month is the worst time to pay because they don’t get paid until the 30th. It’s all about trying to decrease the level of stress people feel when they just feel out of control.
What is your current research focused on?
I’m researching how payment frequency impacts perceptions and behaviors—how wealthy we feel and how that impacts our spending and saving. This is an important question because we are moving into a world where millions of workers can now choose how often they want to get paid (drivers using ridesharing apps, for example). What my coauthor Stephanie Tully and I found was that getting paid more frequently increases subjective wealth perceptions and as a result, we tend to spend more than if we got paid less frequently.